Video Interview: The State of Fintech and Why We Can Expect Significant M&A in the Space for 2023

Last year was the calm before the storm for private fintech companies, so we are going to see a lot of market consolidation this year.

Rocio Wu discusses our State of Fintech Report with Jill Maladrino on Nasdaq TradeTalks, covering how investors weighed the growth potential in the fintech sector in 2022, how they’re being valued now, and what investors can expect in 2023.

Originally published by Nasdaq TradeTalks

Assessing the State of Fintech

Fintech was on fire in 2021. A record 77 fintech companies went public, which included eight of the largest 10 exits in history.

However, in 2022 public investors re-appraised many fintech companies, prioritizing capital efficiency and shifting valuation multiples to align more closely with traditional financial services businesses. The F-Prime Fintech Index declined 72% over the course of 2022. Rising interest rates and macroeconomic uncertainty added to the significant valuation declines with certain fintech verticals seeing larger declines. Despite the drop in valuations, fintech disruptors grew rapidly, continued to capture market share, and give venture investors many reasons for long-term optimism.

New Logos in the Fintech Index

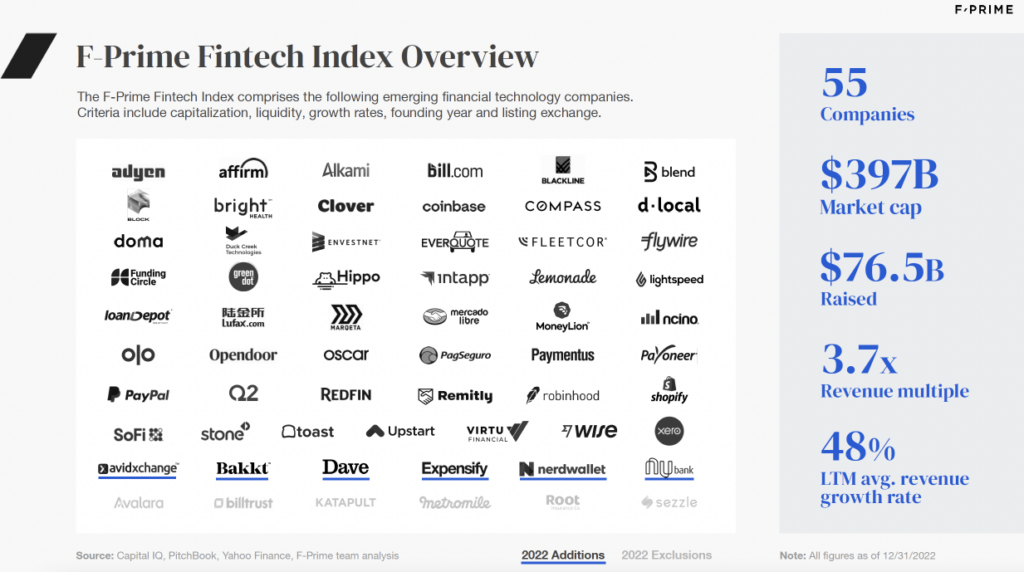
The average company in the Fintech Index lost 56% of its value in 2022. Companies that listed between 2020 and 2022 — two thirds of the companies in the Fintech Index — fared even worse, falling 65%. Because the IPO market came to a halt in 2022, there were few additions to the Index. Of the six new companies added to the Index last year, only Dave went public in 2022. The others — AvidXchangeBakktExpensifyNerdWallet, and Nubank — all went public in Q4 of 2021 and, per our methodology, required 90 days to “season” before we added them to the Index.

We also saw three acquisitions of Fintech Index companies in 2022. Metromile was acquired by Lemonade, Vista Equity Partners took Avalara private, and EQT Private Equity did the same with Billtrust. Meanwhile, Katapult, Root Insurance, and Sezzle failed to meet the criteria to remain on the Fintech Index, and were therefore removed at the end of 2022.
state of fintech 2022

Variation Across Verticals

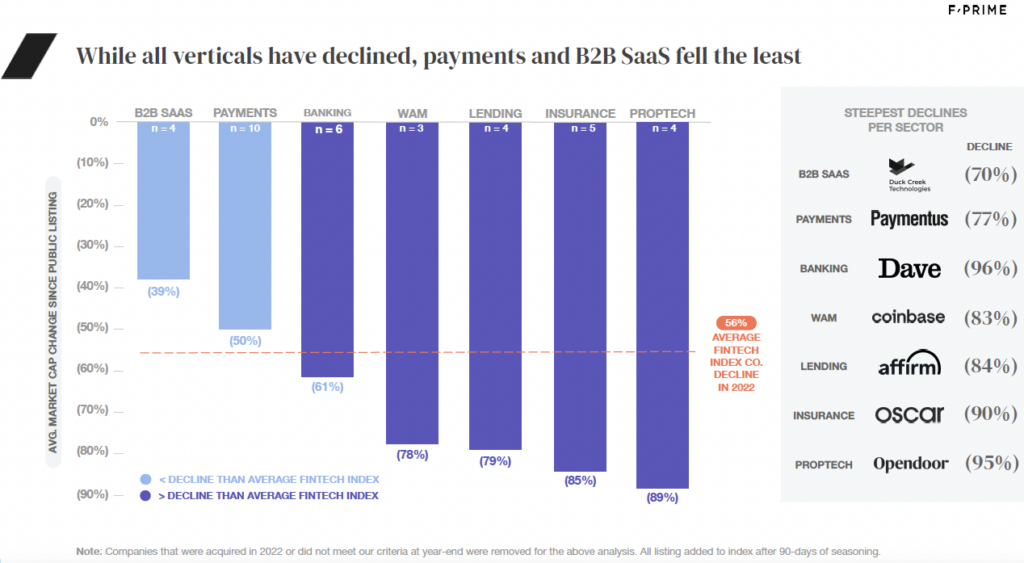
While nearly all tech and fintech stocks fell in 2022, the Fintech Index reveals meaningful differences across fintech verticals. We saw the steepest valuation declines in proptech, insurance, lending, and wealth/asset management — verticals that are especially exposed to rising interest rates and thin liquidity markets. Unsurprisingly, B2B fintech and payment companies saw less than average declines.
state of fintech payments declined the least

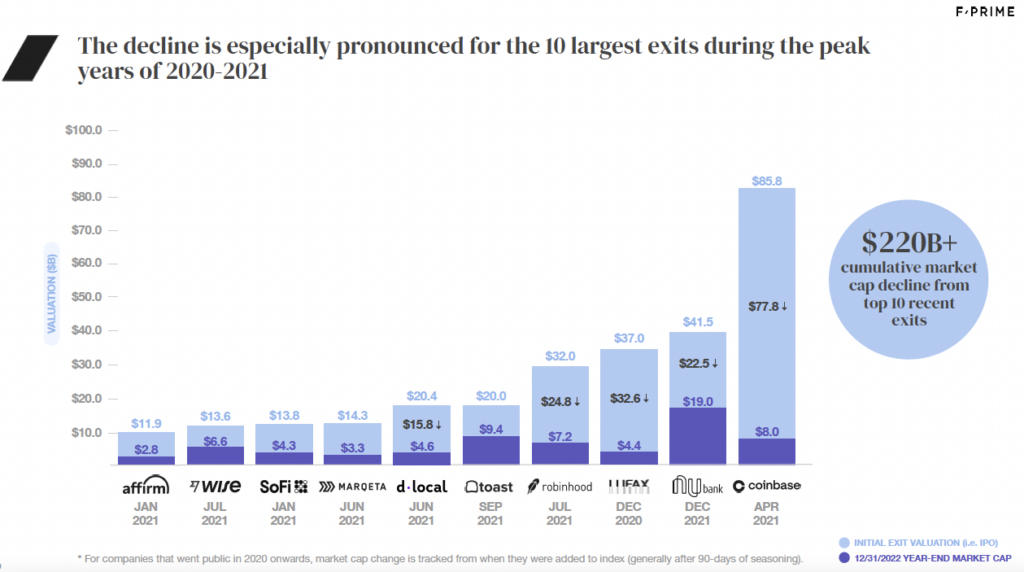
Fintech Index companies that went public in or after 2020 exited at a peak market, leaving them vulnerable to significant losses in the next downturn. Companies like Coinbase saw a 90% decline in market cap over the course of 2022.
fintech decline 2022

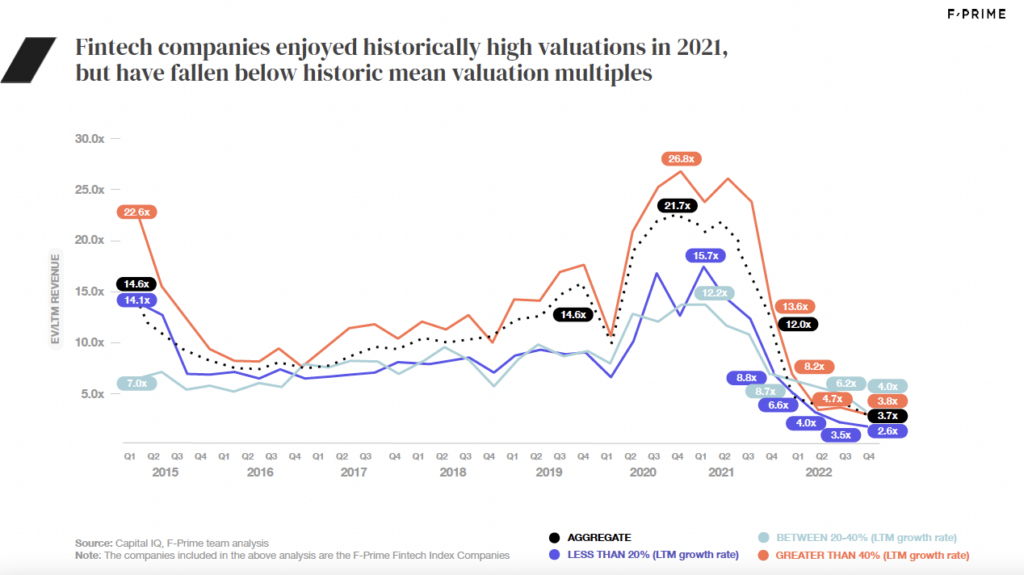
Some of those corrections appear to revert company valuations to historical norms. Others are especially large, with multiples significantly below historical averages as public markets begin to distinguish tech-enabled versions of existing financial institutions from truly disruptive approaches to financial services.
state of fintech multiples

New Metrics to Capture a Diverse Sector

Compared to SaaS companies, fintech business models vary greatly across verticals. Thus, we need to evaluate the diverse set of companies within each fintech vertical distinctively. In response, we are adding new vertical specific metrics to the Fintech Index so they may serve as a quick reference for founders, investors and others to benchmark against recently listed public disruptors and incumbents in the financial services sector.
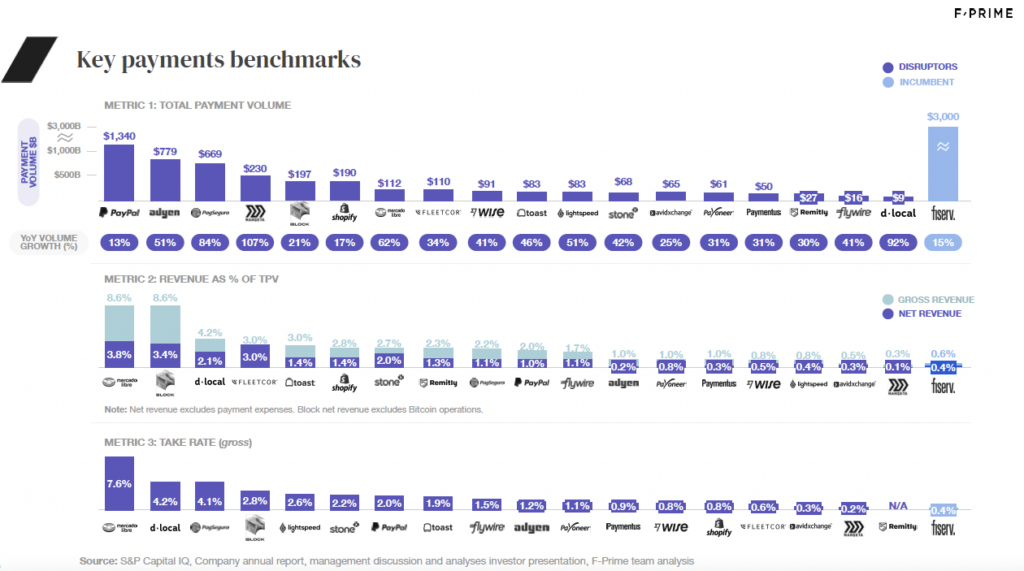
payments benchmarks

In its current state, the Fintech Index can highlight top-performing companies in each category, however over the coming months we will roll out dynamic charts showcasing key benchmarks across fintech verticals.

The Year Ahead

We’re tracking a number of disruptive trends across all fintech verticals, however below are some of the areas we are particularly excited about in 2023:
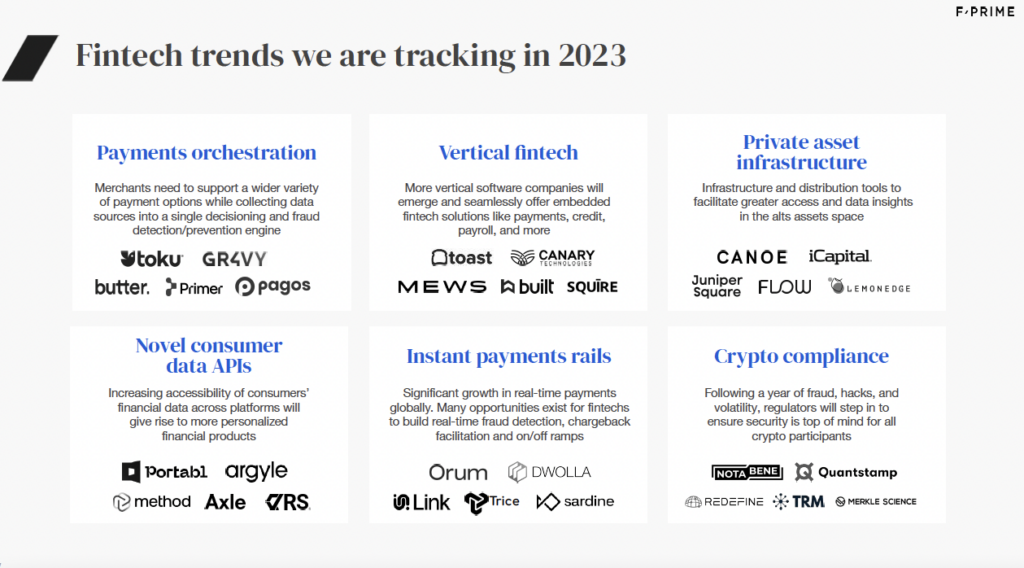
fintech trends we're tracking

While 2022 was a tough year for fintech, we remain steadfast in our conviction that this is a great category to build and invest in. For one, fintechs are still in the early innings of capturing financial services revenue share — right now, fintech companies have captured approximately five percent of total financial services industry revenue.
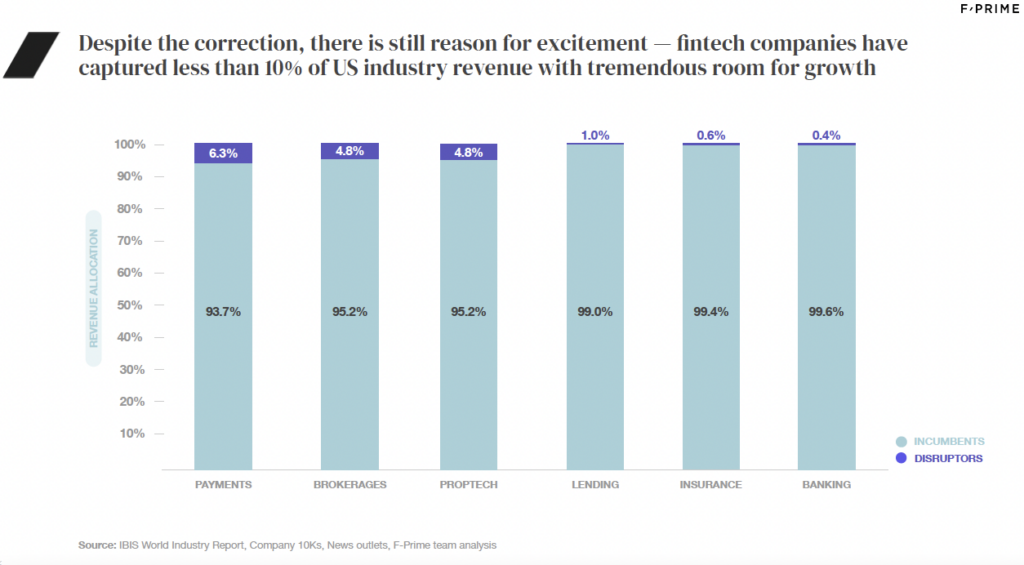
reasons for fintech excitement

Meanwhile, fintech continues to eat the world as the embedding of fintech products accelerates across new verticals. As early backers of Toast and Flywire, we saw this first-hand in the restaurant industry and higher education. We see this in other verticals where disruptors like Shopify, ServiceTitan, Procore, Mindbody, and others are doing the same. Embedded fintech not only centralizes and improves the experience for users — it also increases TAM and makes previously overlooked verticals more interesting as ARPU/ACVs can increase 2–5x.

Finally, disruptors are both growing the pie and taking market share from incumbents. In the first three quarters of 2022, Fintech Index companies grew revenue 45%+ on average, and added $19 billion in revenue collectively to the Index. Furthermore, the vast majority of that growth was organic, as no new companies were added to the Index after Q1 2022.
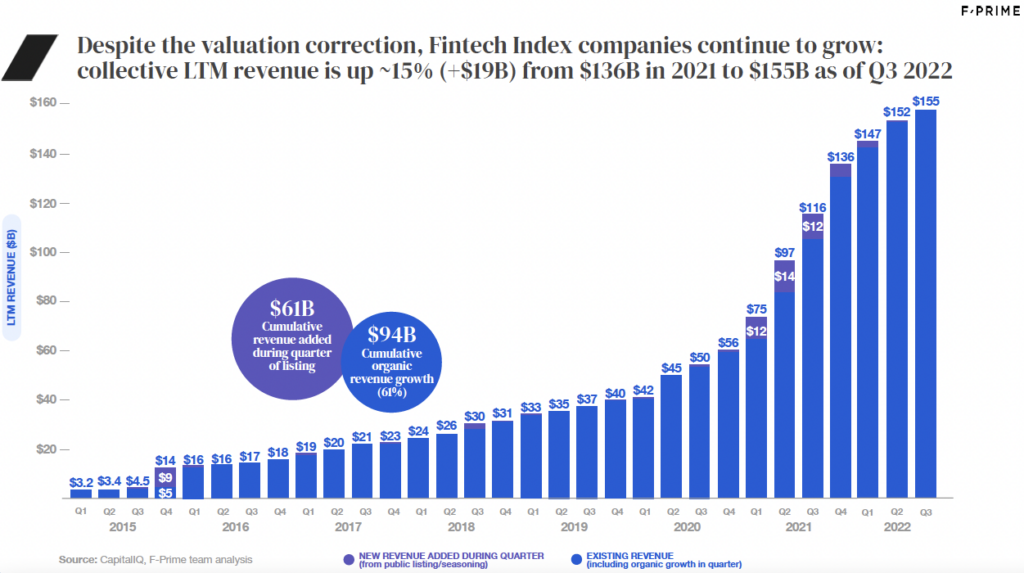
fintech valuation

We also expect M&A to pick up dramatically in 2023 and especially in 2024, as buyers and sellers find valuation alignment. As mentioned earlier, private equity firms have increased their acquisitions of Fintech Index companies and we expect more buyout transactions — for example, DuckCreek is due to be acquired by Vista Equity Partners in 2023. We will remove the company from the Index once the transaction closes, as we did with the three aforementioned acquisitions in 2022.

Beyond that, we encourage you to dive into the report and join us on Thursday March 9th for an online discussion of its findings with the F-Prime team. What do you think of our conclusions? How excited are you for those new dynamic metrics to drop? And what are you most looking forward to in fintech-land in 2023? Drop us a line on Twitter and LinkedIn — and if you’re building or investing in fintech, let’s connect!
Canoe Intelligence

Canoe’s mission is to unlock efficiencies in alternative investment processes by introducing purpose-built automation into the workflows of institutional investors, asset servicers, capital allocators and wealth managers.

Who Will Build the Bloomberg of Private Markets Data?

Our Series B investment in Canoe Intelligence

I recently wrote about the need for a new digital tech stack for the Alternatives fund industry. The human and paper-based workflows of venture capital, private equity, and private credit create a generational opportunity for entrepreneurs to a) digitize investor onboarding, b) modernize the back office, and c) generate an unprecedented layer of analytics-ready private fund data.

Many talented founders are building businesses to address the first two opportunities. It is still early in product execution and adoption, but startups like Flow, Entrilia, Juniper Square, +Subscribe, LemonEdge, PassThrough, Sydecar, Asset Class, and Canopy are building the future of private fund infrastructure.

The Data Problem

The data layer, however, is another matter. Fund managers almost exclusively rely on PDFs to share data with their limited partners (LPs), and there is little sign of this changing soon. We estimate that well over 100 million PDFs are sent annually, with most recipients manually entering the data into their accounting, reporting, and analytics systems.

That is too much redundant data entry, and ultimately leaves a lot of valuable data unextracted and under analyzed. Until fund managers digitize their fund operations and add APIs for data distribution, LPs are going to suffer. Players like Cambridge Associates will retain well-paid analysts to speak with fund managers, gather their data manually, and distribute benchmarks (and yes, really) through more .pdfs.

A Better Future

Now imagine a world where all private equity performance and holdings data is digital, where investors can download historical performance, review investment history, and create their own benchmarks and reporting. It is not hard to imagine because it would look like the public markets, where even Yahoo Finance has decades of analytics-ready data on nearly every equity and debt security in the world.

I anticipate three phases to this transformationFirst, startups must meet the Alternatives industry where it is today – flat files like PDFs and spreadsheets. Domain-specific machine learning (ML) models can automate data extraction, classification, and normalization. While some worry that open-source ML models threaten these businesses, I see startups building defensible businesses across many industries through the thoughtful integration of open-sourced ML-models, proprietary domain-specific AI, and humans. Over time, their focus on one industry also yields a data advantage and network effect –  multiple investors in the same fund using the same quarterly report, for example. Ocrolus in SMB lending, Snapdocs in mortgages, and BenchSci in pharma R&D are all good precedents.

Eventually, fund managers will modernize their accounting and fund admin, and some will distribute data digitally. This will be a great step forward. As an early investor in Quovo, I recall the initial reaction when banks did the same thing. They published APIs and told aggregators like Plaid and Quovo to use them. At first that was concerning, but aggregators quickly realized their data aggregation costs would actually decrease – while their real value-add remained. In Alternatives data, startups that have built strong customer relationships will also benefit; LPs/investors in private funds are really paying them to distribute clean, normalized data from thousands of private funds that lack common data definitions and categorizations.

And that leads to the third phase, where the leaders have the chance to become the Bloomberg of Alts data. It’s hard to believe, but there is no official “security master” for private funds, like we have for stocks and bonds. There isn’t even a common taxonomy for fund returns – I say MOIC; you say CoC. And, of course, not all funds report all metrics. With access to years of fund performance data from a broad universe of private funds, startups will have a remarkable opportunity to help investors analyze fund performance better and faster. Another exciting implication is that easily accessible alts data and analytics will lower the barrier for financial advisors and accredited investors to participate. Ultimately this is great for advisors who need to explain their recommendation to clients, and for private funds who are working to expand their investor bases.

Partnering With Canoe Intelligence to Build that Future

Abdul and I, and everyone at F-Prime Capital, are thrilled to partner with Canoe Intelligence in their pursuit of this goal. Together with Alston Zecha and Jens Neisius from our European fund Eight Roads Ventures, we led their recent Series B and are impressed with everything Canoe has accomplished already. They have a great ground game, stellar customer list, top-quartile SaaS metrics and a leading tech platform that is only getting better with scale and network effects. We have wanted to be a part of the solution in Alternatives data for many years, and we’re excited to see Canoe lead the industry. Paddle on JasonMikeVishalMichelleJoshSethTim, and everyone on the Canoe team!

Toku

Toku is a payment orchestration company that offers a solution for collecting recurring payments in LatAm. It has three main value propositions: 1) increase payment acceptance rate via dynamic routing; 2) incur the lowest possible cost by using account-to-account payment; 3) have the best-automated payment experience.

How Startups Can Help You Win the Talent War With Tailored Employee Benefits

The employer sales channel has inherent and often overlooked advantages.

In 2021, nearly 50 million workers voluntarily left their jobs. The median tenure of employees over the age of 25 has dropped from 5.5 to 4.9 years since 2014. On average, employees 25 to 34 now stay at jobs for less than three years.

This isn’t just “quiet quitting.” U.S. workers are ready to move on from their current jobs — and they’re sending that message loud and clear.

In a story for VentureBeat, John Lin and Sarah Lamont outline how a tight labor market poses a number of opportunities for certain startups to sell their products and services as employee benefits.

Originally published in VentureBeat. Read the full story here.

What Founders Need to Know Before Selling Their Startup

The most common theme for these conversations was simply: “I wish I had known then what I know now.”

Throughout his career, David has experienced 11 different acquisitions from multiple perspectives: as a founder, an investor, and a Board member. Recently, he recently went on a listening tour to compare his experience with the post-acquisition stories of a wide range of acquired founders — and then shared his findings with Harvard Business Review.

Originally published in Harvard Business Review. Read the full story here.

Deal Engine

Deal Engine is a travel software company with a mission to bring digital transformation to the travel industry. Utilizing proprietary AI and APIs, Deal Engine brings automation to travel, eliminating manual processes, and making sure people spend their time where they generate more value.

Announcing our Investment in Deal Engine

Our latest Seed round in the travel tech space

Almost three decades into selling flights online (thanks Travelocity!), the cobweb of infrastructure that supports the travel industry has not modernized to meet the complexity growing at the surface.

Code-share agreements, ancillaries, vacation packages, layers of wholesalers, and other “business innovations” have led to booking and customer service nightmares for passengers, agencies, and airlines themselves. A simple change or refund often requires a call to customer service (have four hours to wait?) that descends into manual reading and interpretation of fare rules, calls from OTAs to airlines for clarifications, tax estimations (you’d be surprised), and other unenviable manual tasks. As important as the Global Distribution Systems (GDS’s) have been in digitizing the travel market, the pandemic highlighted the challenges the industry faces when so many of its “normal” operational processes still require human artistry to Get Stuff Done.

We believe Deal Engine, which announced its $5.3M Seed round led by F-Prime Capital today, has an opportunity to be the travel industry’s agent for digital transformation. By building a new infrastructure layer that abstracts away the complexities of fare rules and travel policies with a powerful machine-learning based engine, Deal Engine enables their partners (OTAs, TMCs, or airlines) to automate the transactions that used to be manual. The most complex changes and refunds can now be executed with a simple API call, initiated by a customer service rep or the customer themselves with the push of a button. This capability has the potential to transform the post-booking customer experience, shifting focus from cost reduction to revenue generation — all while giving the consumer the amazing experience that online travel promises.

The leadership team at Deal Engine — including Alex JaraDavid Gomez-Urquiza and Isabel Carrera Quiroga — possess tremendous courage and domain expertise to tackle such a massive problem in travel. They have not been shy about bringing their disruptive solution to the behemoths we all know and sometimes love, leading Deal Engine to serve a who’s who of players in the travel industry. Betsy Mulé and I are excited to be partnering with this team, which is doing the truly hard work of making travel better for all of us.

Shout out to Thayer VenturesPAR Capital ManagementPlug and Play Tech Center and Brook Bay Capital, LLC, who also participated in the round.

Hannah Arnold

Hannah is a Venture Partner at F-Prime and leads Business Development and Mortgage at Argyle. Previously she was on F-Prime’s tech investment team focused on early-stage FinTech investments. Prior to joining F-Prime, Hannah worked closely with startups in Johannesburg as an associate with Secha Capital, where she spent every day on the ground helping teams in Secha’s portfolio scale. She was a consultant with Bain & Company in Atlanta, where she served large tech clients and worked extensively with the Private Equity practice on deals spanning healthcare, e-commerce and industrials. She began her career working for non-profits in international development, where she saw firsthand the impact that innovative financial products can have on people’s lives. Hannah received her BA in Public Policy from Duke University.